

Expense IQ Money Manager
by Handy Apps
3.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.2
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
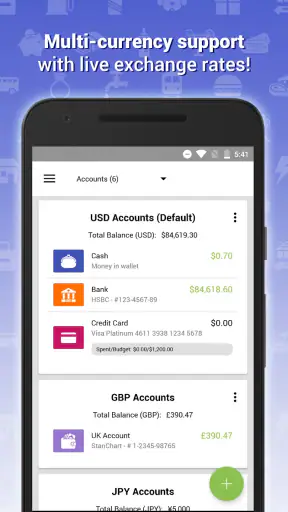
 Analysis by Getfullapps
I approached Expense IQ Money Manager as a practical question rather than a hunt for the most impressive finance app: can it make everyday money decisions easier without turning budgeting into another chore? After using it as a personal finance tool, my answer is yes, with an important qualification. It is most useful when you want to record spending, plan limits, and remember bills in one place, but it asks you to stay involved. This is not the kind of app that replaces good habits by itself.
Developed by Handy Apps, this free finance app combines expense tracking, budget planning, and bill reminders. It is available for Everyone, runs on Android versions from 4.4 onward, and its current version is 2.3.2. The app has passed one million installs, with a 3.2 average from around 23 thousand ratings and roughly 2.8 thousand written reviews. Those figures suggest a product with a sizable audience but a mixed experience, which matches my impression: the core idea is useful, while the day-to-day feel depends heavily on how carefully you set it up.
How I would decide whether Expense IQ fits
The first decision is how much control you want over your financial records. If you prefer typing in purchases yourself and assigning them to categories, this app gives you a clear place to build that routine. If you expect your bank activity to appear automatically with almost no attention, you should examine other types of money tools before committing. Expense IQ makes sense as an intentional tracker, not as a completely hands-off financial dashboard.
The second question is whether your financial life is simple enough for a personal ledger. A single salary, regular household bills, cash purchases, subscriptions, and a few savings targets are a comfortable match. The app can also be useful for someone trying to understand where money disappears during a month, because the value comes from seeing individual spending decisions grouped into a broader picture.
I would be more cautious if you need sophisticated investment monitoring, shared household workflows, or a polished system that automatically connects every account. Those needs belong to a different part of the finance-app market. Expense IQ is better understood as a focused money manager than as a complete financial institution in your pocket.
There is also a question of patience. Manual tracking works only when entering a purchase becomes as ordinary as checking a notification. During my evaluation, the strongest results came from recording a transaction immediately or at the end of the same day. Waiting until the weekend made small cash purchases harder to remember, and a budget can look reassuringly accurate while quietly missing the unrecorded coffee, parking charge, or lunch.
The setup matters more than it first appears
I recommend beginning with a small number of useful categories rather than trying to describe every purchase perfectly. Broad groups such as groceries, transport, housing, eating out, and personal spending are easier to maintain than a maze of tiny labels. The goal is not to create an accounting system that impresses you on day one; it is to create one you will still use after a busy week.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
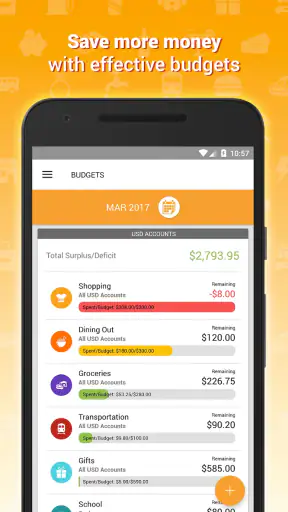
Budgets are more helpful when they reflect the way you actually think about spending. A monthly limit for dining out can answer a real question, while a dozen narrow limits may create noise. I found that a budget should be a warning line, not a punishment. If the number is unrealistic, repeatedly exceeding it teaches you nothing except that the setup needs changing.
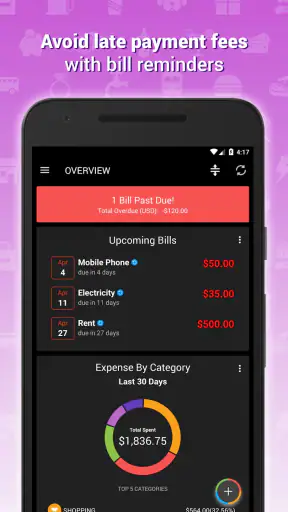
Bill reminders deserve separate attention. They are useful for fixed obligations that are easy to overlook, especially when several payments arrive around the same part of the month. I would not treat a reminder as proof that a payment has been completed. The safer workflow is to use the reminder to prompt a check, then record the payment or update its status yourself. That small distinction prevents a planning tool from becoming a source of false confidence.
One practical tip is to separate predictable bills from flexible spending when reviewing the month. Rent, utilities, and recurring services tell you what is already committed. Groceries, entertainment, and impulse purchases show where you still have room to change course. Mixing the two into one total can make your finances feel more mysterious than they are.
Where it wins over a basic notes app or spreadsheet
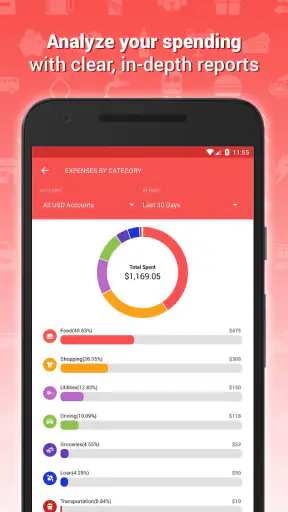
A notes app can record amounts, and a spreadsheet can calculate totals, but both require you to design the system. Expense IQ starts with the idea that a purchase belongs to a financial record rather than a loose list. That difference becomes valuable when you want to review spending by category, compare it with a planned limit, and keep upcoming bills in the same general workflow.
I also prefer a dedicated tracker when I am trying to build a habit. Opening a finance app creates a clearer mental boundary than adding “groceries, 18” to a general note that also contains errands and ideas. The app’s purpose helps reduce the chance that financial information becomes scattered across notebooks, messages, and memory.
Another advantage is the combination of short-term and recurring thinking. An expense entry answers what happened. A budget asks how much room remains. A bill reminder asks what is about to happen. These are different questions, and keeping them close together makes the app more useful than a simple spending log.
For a realistic example, imagine I receive my monthly income and immediately record the rent and other fixed obligations. I then set a grocery limit and a separate amount for eating out. During the second week, an unexpectedly expensive dinner pushes the restaurant category close to its boundary. The useful moment is not the end-of-month report; it is seeing that pressure early enough to choose cheaper meals for the remaining days. That is where a manually maintained budget can change behavior.
Small workflows that make the app more useful
My first non-obvious recommendation is to perform a quick evening reconciliation rather than trying to reconstruct the entire week. I would check card receipts, cash in my wallet, and any purchase notifications, then enter the missing items while the context is still fresh. This takes less effort than a large weekend audit and makes the categories more trustworthy.
My second recommendation is to use the app as a review tool, not only as an input box. Once a week, I would look for repeated small purchases rather than focusing only on the largest transaction. A single large bill is usually visible already; several modest convenience purchases are more likely to reveal a habit that can actually be changed.
Third, I would create a personal rule for unusual expenses. A medical purchase, annual renewal, or one-off repair should not automatically make a normal monthly category look permanently unrealistic. Record it accurately, but interpret it separately when deciding next month’s limit. Otherwise, one unusual event can distort the budget you use for ordinary life.
A fourth useful trade-off is speed versus detail. Recording every purchase with extensive notes may produce a richer history, but it can also make you abandon the habit. For routine spending, a consistent category and amount are often more valuable than perfect descriptions. Save extra detail for transactions you expect to question later.
Where another kind of finance app may fit better
Expense IQ is not automatically the best choice for people who want their finances to update themselves. An account-connected app may be more convenient if you have many cards or accounts and dislike manual entry. That convenience comes with its own considerations, including how much control you want over connections and how much you trust automated categorization. I would choose the connected approach for visibility across a complicated financial life, but the manual approach for deliberate spending awareness.
A spreadsheet may suit you better if you need custom formulas, detailed forecasting, or a structure built around irregular freelance income. A spreadsheet takes more effort to design, yet it can adapt to unusual financial models in ways a ready-made money manager may not. In contrast, Expense IQ is more approachable when you want a prepared workflow rather than a blank grid.
Couples should think carefully before treating it as a shared household system. If both people need to enter transactions, approve changes, or see the same live picture, a tool designed around collaboration may be a smoother fit. Expense IQ can still help one person manage the household ledger, but that is different from giving two people an equally convenient shared workspace.
People focused on investments, taxes, business accounting, or debt repayment strategies may also outgrow it. A general expense tracker can show where money goes, but it should not be mistaken for specialized professional software. I would use it alongside a more suitable tool if those areas are central to your financial decisions.
What the free model means in practice
The app is free to download and use as a starting point, but in-app purchases range from $3.49 to $124.99 per item. That wide range is a reason to inspect the upgrade screen carefully before paying. I would first build a complete routine with the available free experience and decide whether the app is genuinely helping me before considering any purchase.
The important cost is not only money. Switching to a new finance app means recreating categories, budgets, bill schedules, and several weeks or months of personal history. Even when importing information is possible in a particular workflow, cleaning old records and making categories consistent takes attention. That is why I would test Expense IQ with a limited period before moving my entire financial routine into it.
A sensible trial method is to choose one account or one spending area, such as household purchases, and track it consistently. After a couple of weeks, ask whether the records are clear enough to guide a decision. If you are still postponing entries or feeling confused by the categories, adding more data will not solve the basic problem. The right app is the one whose routine you can maintain.
I would also keep a simple backup habit outside the app for important figures, particularly before making a major financial decision or changing devices. That is not a criticism unique to this product; personal finance records deserve care wherever they live. The less often you need to reconstruct history, the more confidently you can use the app’s summaries.
Everyday friction I would want you to expect
Manual entry is the central limitation. It gives you control and can make spending more visible, but it is also the reason the app may feel demanding. A person who makes many small purchases, uses several payment methods, or shares expenses frequently may find the upkeep tiring. The app cannot provide meaningful guidance from transactions that never make it into the record.
There is also a natural tension between reminders and responsibility. A notification can help me remember a bill, but it does not know whether the amount changed, whether a payment failed, or whether I paid through another route unless I keep the record current. I would use reminders as prompts for action, not as an automated bill-management service.
The 3.2 average rating indicates that the overall experience has not been equally satisfying for everyone. I would not treat that number as a final verdict, because finance apps often divide users between people who enjoy manual control and people who expect automation. Still, it is a useful signal to keep expectations realistic: this is a practical tool that may require adjustment rather than a universally effortless solution.
The minimum Android requirement of 4.4 makes the app accessible to older devices, which can be helpful if you are using an aging phone for basic financial tasks. At the same time, anyone expecting the newest platform conventions should judge the interface by actual comfort rather than assuming that a finance app with broad device support will feel modern on every handset.
Who should use it and who should skip it
I would recommend Expense IQ to someone who wants a dedicated place for everyday spending, prefers to stay in control of entries, and is willing to spend a few minutes maintaining the record. It is particularly suitable for a person who keeps wondering why the month feels expensive despite having a reasonable income. Categorizing real purchases can turn that vague concern into specific choices.
It can also suit students, first-time budgeters, and households with fairly predictable commitments, provided they understand that consistency matters more than elaborate setup. The Everyone content rating makes it broadly approachable, and the free entry point lowers the barrier to trying a structured method without immediately committing to a paid service.
I would skip it if automatic account aggregation is non-negotiable, if you need advanced investment or business accounting, or if you know you will not record cash and card purchases regularly. In those situations, the app’s central strength becomes a weakness because the process depends on participation. A different category of tool may save more time and produce a more complete picture.
My recommendation after weighing the trade-offs
Expense IQ is worth trying when your main goal is awareness rather than automation. I like the way it brings spending records, planned limits, and bill prompts into one personal workflow. It is more purposeful than a notes list and less intimidating than building a financial system from scratch. The best results come from using it lightly but consistently: record promptly, keep categories understandable, and review patterns before changing the budget.
I would not pay for extra functionality immediately, especially with individual in-app purchase prices ranging from $3.49 to $124.99. First determine whether the habit survives a normal busy month. If it does, the app may become a dependable companion for everyday money decisions. If it does not, the problem is probably the workflow rather than a missing feature, and an automated or more specialized alternative may be the better investment.
My final view is cautiously positive. Expense IQ is a useful free finance app for people who want to see their choices clearly and are prepared to do the recording themselves. It will not remove the work of managing money, and it is not the right answer for every financial situation. But for a straightforward personal budget, its combination of expense logging, limits, and bill reminders gives me enough structure to recommend it to a friend who is ready to build a real tracking habit.
Pros
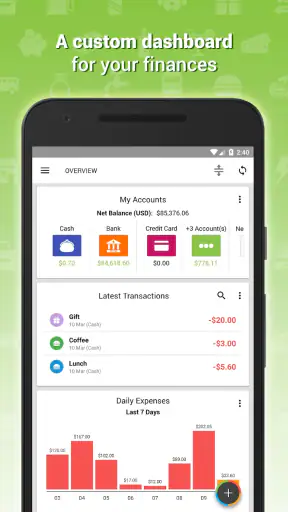
- Clear charts make spending trends easy to understand.
- Supports recurring transactions for regular bills and income.
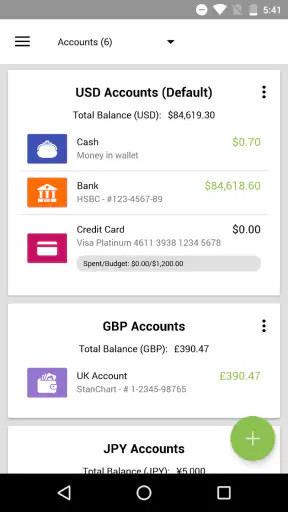
- Multiple account types help separate cash, cards, and bank balances.
- Useful search and filters make past transactions quick to find.
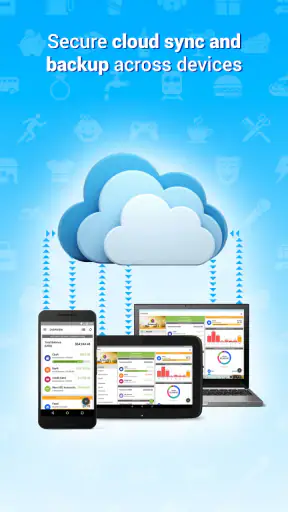
- Backup and restore options help protect your financial records.
Cons
- Some advanced features may require the premium version.
- Manual entry can become time-consuming for frequent daily purchases.
- Bank synchronization availability may vary by country or institution.
- The interface can feel crowded for users managing many accounts.
- No budgeting tool can fully replace careful financial planning.
FAQs for Expense IQ Money Manager
What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you track income, expenses, bills, budgets, and savings goals in one place. After exploring its main tools, I found it especially useful for users who want a clearer view of daily spending without relying on spreadsheets. You can organize transactions by categories, review financial summaries, and monitor whether your spending stays within planned limits.
Does Expense IQ Money Manager support budgeting and expense tracking?
Yes. The app lets you record expenses and income, assign categories, and create budgets for areas such as groceries, transportation, entertainment, or household bills. Its reports and summaries make it easier to identify spending patterns over time. However, the usefulness of the budget feature depends on entering transactions consistently, since inaccurate or incomplete records can make the financial overview less reliable.
Can I manage bank accounts and multiple currencies in Expense IQ?
Expense IQ Money Manager is designed to help users organize information from multiple financial accounts, including cash, bank accounts, credit cards, and other personal sources. Depending on the version and platform, some account-management or currency features may vary. Before downloading, users who travel frequently or manage international finances should check the current app listing to confirm supported currencies and account options.
Is my financial information safe in Expense IQ Money Manager?
Because the app can contain sensitive information about income, purchases, accounts, and bills, privacy and device security are important considerations. Expense IQ may offer protections such as app access controls or backup-related options, but available safeguards can depend on the operating system and selected settings. I recommend reviewing its privacy policy, limiting unnecessary permissions, and using a secure device lock before storing detailed financial data.
Is Expense IQ Money Manager free to download and does it contain premium features?
Expense IQ Money Manager may be available as a free download, but some advanced tools can require in-app purchases or a premium upgrade, depending on the current Android or iOS version. Features such as expanded reports, additional customization, cloud-related services, or an ad-free experience may not be included in the basic version. Check the store page carefully for pricing, subscriptions, and trial conditions before installing.

Expense IQ Money Manager
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@handyappsforlife.com, visit http://www.expense-iq.com/, or review their http://www.handyappsforlife.com/privacy-policy.










